To view this message as a word file, click here.
To view this message as a pdf file, click here.
- Exchange Rate Development
A weakening of the shekel alongside a mixed trend of the US dollar worldwide.
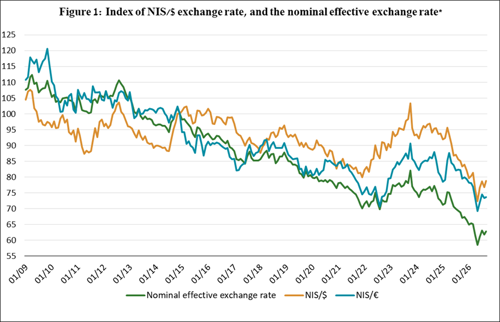
In the third quarter of 2026, the shekel weakened by approximately 2.9 percent against the US dollar and by about 2.4 percent against the euro. In addition, the shekel weakened by about 2.8 percent against the currencies of Israel's main trading partners, in terms of the nominal effective exchange rate (i.e., the trade-weighted average shekel exchange rate against those currencies).
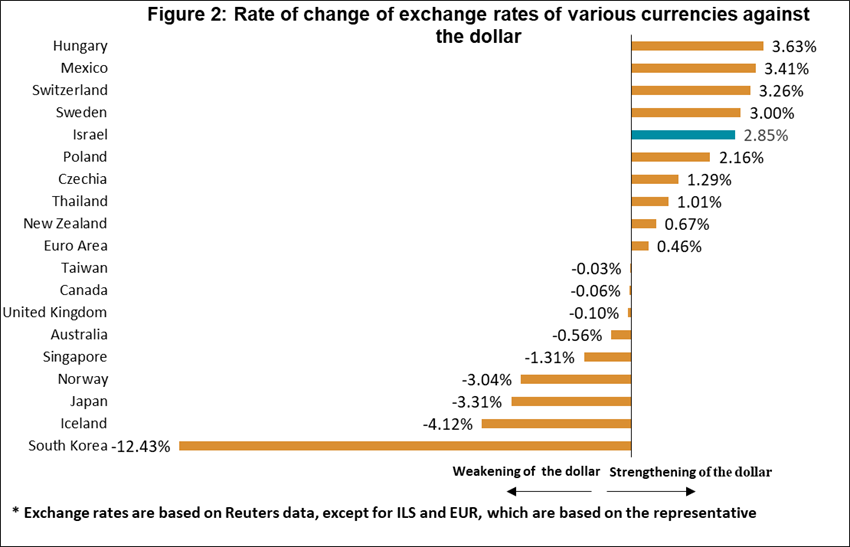
During the third quarter, the US dollar was mixed against the major currencies (Figure 2). The dollar weakened by about 12.4 percent against the South Korean Won and by about 3.3 percent against the Japanese yen, while it strengthened by about 3.3 percent against the Swiss franc and by about 0.5 percent against the euro.
- Exchange Rate Volatility
A decline in actual volatility alongside an increase in implied volatility
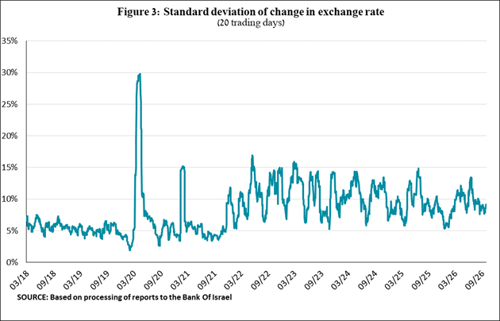
The actual standard deviation of changes in the shekel/dollar exchange rate, which represents its actual volatility, declined by 1.7 percentage points during the quarter, to an average level of 9.0 percent.
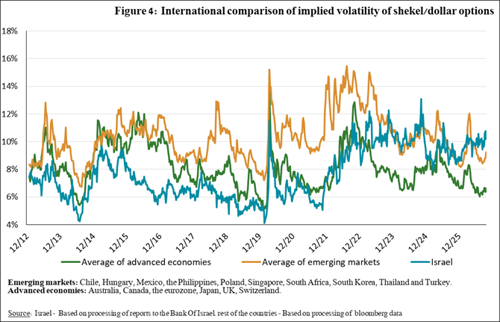
The average implied volatility in over-the-counter shekel/dollar options—those traded outside the stock exchange—which is an indication of expected exchange rate volatility, increased by 0.1 percentage points, to an average level of about 10.1 percent at the end of the quarter. This is alongside the average level of implied volatility in foreign exchange options in emerging markets, which declined by about 1.3 percentage points to 8.7 percent at the end of the quarter. In addition, there was a decline of about 0.6 percentage points in the average level of implied volatility in advanced economies, to about 6.4 percent at the end of the quarter (Figure 4).
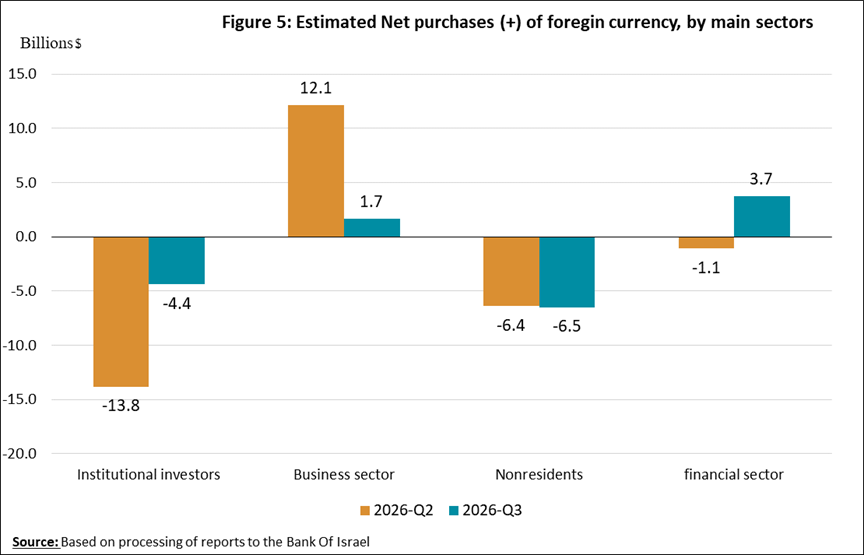
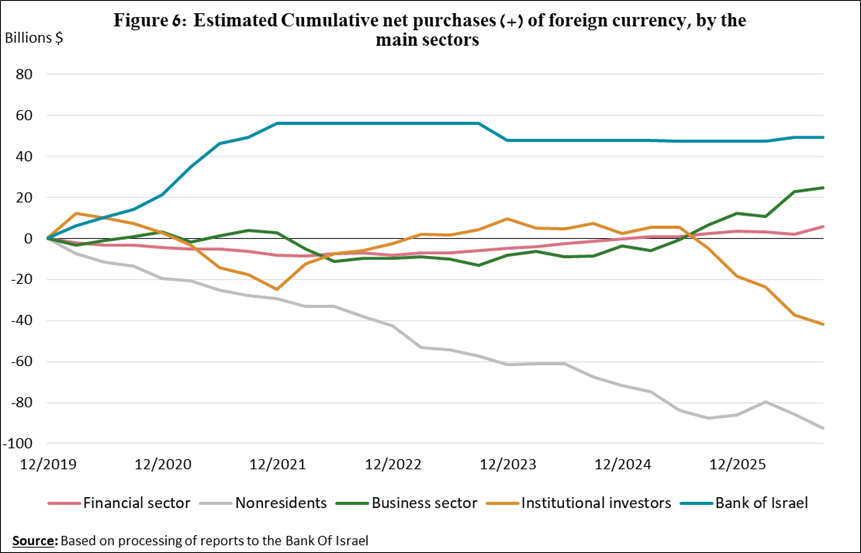
An estimate of activity by the main segments in the foreign exchange market indicates a change in the composition of activity in the third quarter. During the quarter, the financial sector moved to net foreign exchange purchases, while the business sector significantly reduced its net foreign exchange purchases. Institutional investors reduced their net foreign exchange sales, and nonresidents continued to make net foreign exchange sales.
The institutional investors—pension funds, provident funds, and insurance companies—reduced their net foreign exchange sales to about $4.4 billion during the quarter, compared with sales of about $13.8 billion in the previous quarter.
The business sector reduced its net foreign exchange purchases to about $1.7 billion in the third quarter, compared to sales of about $12.1 billion in the previous quarter.
Nonresidents continued to make net foreign exchange sales of about $6.5 billion, compared with net sales of about $6.4 billion in the previous quarter.
The financial sector (mainly the banks) transitioned to net foreign exchange purchases of about $3.7 billion in the second quarter, compared with net sales of about $1.1 billion in the previous quarter.
The Bank of Israel did not make net foreign exchange purchases during the quarter. In the previous quarter it made net foreign exchange purchases of about $1.8 billion.
- Trading Volume in the Foreign Currency Market—Tables and Figures
Trading volume vis-à-vis the domestic banking system[3]
The average daily trading volume declined by about 9.1 percent during the third quarter, to $16 billion, with most of the decline coming from spot and forward transactions.
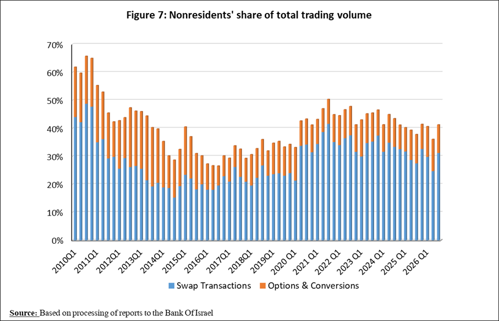
Nonresidents' relative share of total trading volume vis-à-vis the domestic banking system (spot and forward transactions, options, and swaps) increased by about 5.2 percentage points to about 41.4 percent at the end of the third quarter.
|
Forex transactions with domestic banks, by instruments and derivatives ($ million) |
||||||
|
|
|
|
|
|
|
|
|
|
|
Conversions (1) |
Swaps1 (2) |
Cross Currency swap2 (3) |
Options3 (4) |
Total volume of trade (1)+(2)+(3)+(4) |
|
Third quarter 2026 (Not final) |
Total |
241,401 |
733,942 |
4,323 |
29,105 |
1,008,771 |
|
Daily average 63 days) |
3,832 |
11,650 |
69 |
462 |
16,012 |
|
|
Nonresidents |
92,421 |
314,369 |
1,136 |
9,483 |
417,408 |
|
|
of which Foreign financial institutions |
91,436 |
314,369 |
1,136 |
9,476 |
416,417 |
|
|
Residents |
148,980 |
419,573 |
3,187 |
19,622 |
591,363 |
|
|
of which Real sector |
56,625 |
41,009 |
469 |
12,095 |
110,198 |
|
|
Financial sector |
38,758 |
178,877 |
878 |
794 |
219,306 |
|
|
Institutions (incl. insurance companies) |
27,416 |
169,576 |
0 |
4,026 |
201,018 |
|
|
Individuals |
7,885 |
4,766 |
0 |
85 |
12,737 |
|
|
Other4 |
985 |
0 |
0 |
7 |
992 |
|
|
Domestic banks5 |
10,327 |
14,200 |
242 |
2,035 |
26,804 |
|
|
Second quarter 2026 |
Total |
281,076 |
685,734 |
1,857 |
35,845 |
1,004,512 |
|
Daily average (57 days) |
4,931 |
12,030 |
33 |
629 |
17,623 |
|
|
Nonresidents |
105,280 |
248,274 |
1,008 |
8,957 |
363,518 |
|
|
of which Foreign financial institutions |
104,406 |
248,274 |
1,008 |
8,846 |
362,534 |
|
|
Residents |
175,796 |
437,460 |
849 |
26,888 |
640,994 |
|
|
of which Real sector |
58,807 |
37,010 |
479 |
15,064 |
111,361 |
|
|
Financial sector |
49,440 |
208,856 |
59 |
1,910 |
260,265 |
|
|
Institutions (incl. insurance companies) |
39,110 |
139,285 |
0 |
6,216 |
184,611 |
|
|
Individuals |
7,904 |
3,318 |
0 |
90 |
11,312 |
|
|
Other4 |
873 |
0 |
0 |
111 |
985 |
|
|
Domestic banks5 |
11,876 |
20,747 |
81 |
2,959 |
35,663 |
|
|
|
|
|
|
|
|
|
|
|
1 Only one leg of the swap, i.e., the nominal value of the transaction (in accordance with the BIS definition) |
|||||
|
|
2 The exchanged founds through Cross Currency Swap transactions considered for the volume, as one leg only in cases where the two legs offset each other. |
|||||
|
|
3 The national value, that includes purchases and sales of put and call options. |
|||||
|
|
4 Including other entities such as portfolio managers, nonprofit organizations, national institutions, and those not included elsewhere. |
|||||
|
|
5 Total interbank trade, divided by 2 |
|||||
Estimated total trading volume[4]—domestic banking system and foreign reporting entities
The estimated total activity in transactions against the shekel, as reflected in reports from the domestic banking system and foreign reporting entities, indicates that nonresidents’ share of trading volume in spot and forward transactions (excluding swaps and options) was about 87 percent in the third quarter.
Trade between nonresidents constituted about 79 percent of the volume, which had a daily average of about $19.7 billion.
|
|
|
Relative share of total trading volume |
|
|
||
|
|
|
Trade between nonresidents |
Trade between a nonresident and a resident1 |
Trade between the domestic banking system and residents |
Total volume ($ million) |
Daily average ($ million) |
|
2026-Q3 |
Trading volume in spot and forward transactions |
79.4% |
8.9% |
11.7% |
1,244,522 |
19,754.32 |
|
Trading volume in swap and options transactions |
54.3% |
21.3% |
24.4% |
1,808,980 |
28,714 |
|
|
2026-Q2 |
Trading volume in spot and forward transactions |
77.4% |
9.7% |
12.9% |
1,336,110 |
23,441 |
|
Trading volume in swap and options transactions |
54.6% |
18.2% |
27.1% |
1,701,854 |
29,857 |
|
|
1 Trade between a nonresident and a resident includes: (a) reports by foreign reporting entities regarding transactions with residents; and (b) reports by domestic banks regarding transactions with nonresidents. |
||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
[1] For additional information on the segments’ activity in the foreign exchange market, see “Statistical Bulletin” 2024—Chapter D.
[2] The main segments presented do not make up the entire market. For additional information, see the section on “The Database of Foreign Exchange Market Activity” in the Bank of Israel’s “Statistical Bulletin” for 2024.
[3] From the beginning of 2020, the data do not include branches of foreign banks in Israel.
[4] Total trading volume is an estimate of total activity in transactions against the shekel, based on reports by the domestic banking system and by foreign reporting entities.